
Life Insurance Laddering Strategy Explained
Quick Summary: Life insurance needs can change as your family, debts, home, and long-term goals change. At Wessel Insurance Services, Inc., we help individuals and families across Maryland explore life insurance strategies that can align coverage with different stages of life. Life insurance laddering uses multiple policies with varying terms and coverage amounts, creating a flexible approach to protecting the responsibilities that matter most.
What Is Life Insurance Laddering?
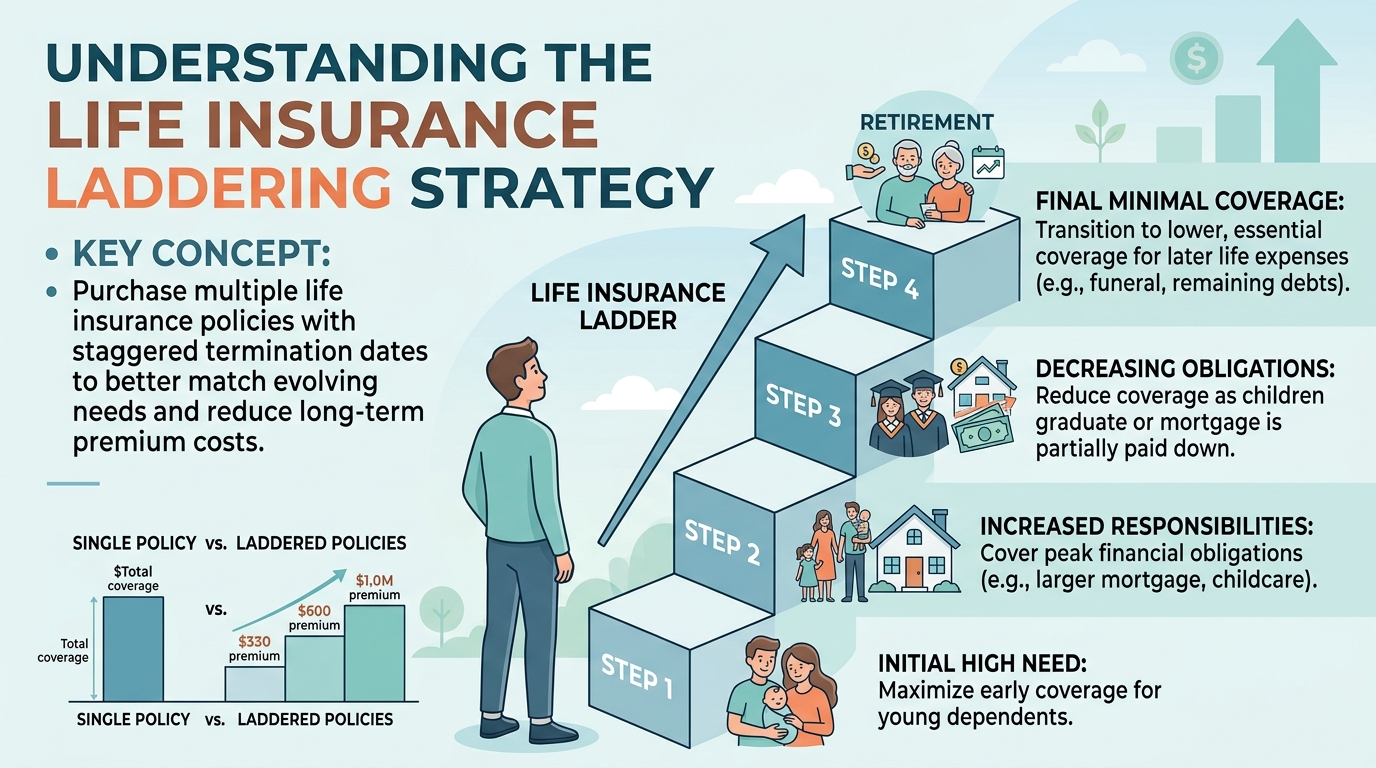
Life insurance laddering is a strategy that uses more than one life insurance policy rather than relying on a single large policy for every need and every stage of life. Each policy can have its own coverage amount and term length, allowing it to be connected to a specific financial responsibility.
For example, a family may have one policy intended to help address short-term debt and another designed to provide longer-lasting support for a mortgage or children’s education. Instead of keeping the same level of life insurance coverage in place for decades, the overall protection can decrease as certain obligations are expected to end.
This approach can make a life insurance plan feel more personal and adaptable. As an independent insurance agency in Jarrettsville, Maryland, Wessel Insurance works with clients to consider how current needs and future priorities may fit into a broader insurance plan.
Aligning Life Insurance With Life’s Financial Milestones
Financial priorities do not always remain the same. Purchasing a home, getting married, welcoming children, building a career, and paying down debt can all affect the amount of financial protection a household may need.
One potential advantage of life insurance laddering is the ability to connect coverage to those changing responsibilities. A shorter-term policy may be used to help protect against early-career debt, including student loans or other balances. A longer-term policy may be intended to help support a family while children grow up, attend school, or while a mortgage remains unpaid.
By organizing policies around individual obligations, a life insurance ladder can allow coverage to change over time in a more intentional way. When a responsibility is paid off or otherwise ends, the policy associated with it may expire, while other coverage continues for ongoing needs.
How Laddering May Help Manage Life Insurance Costs
Cost is another reason some people look into a laddering strategy. In many cases, a shorter-term life insurance policy may cost less than coverage with a longer term. Matching a policy’s duration to the expected length of a financial obligation may help avoid paying for a larger amount of coverage after that particular need has passed.
Consider a major debt that is expected to be paid off within 10 years. Maintaining a large amount of insurance specifically for that debt far beyond its payoff date may not be necessary. With a laddering approach, coverage connected to that obligation can end when the obligation is expected to end.
That said, lower coverage over time is not appropriate for every household. Some people may continue to have dependents, long-term debt, or other ongoing responsibilities. For those individuals, allowing coverage to decline may not reflect their actual needs. Reviewing your circumstances and comparing life insurance quotes with an experienced insurance professional can help clarify the available options.
Building Flexibility Into Your Insurance Plan
Life can take unexpected turns, and financial plans often need to adjust along the way. Marriage, a new child, a career transition, a home purchase, or a change in debt can all affect a family’s life insurance needs.
A laddering strategy can offer flexibility because several policies work together rather than placing every need into one policy. This can make it easier to structure coverage for both immediate responsibilities and longer-term goals without having to replace an entire life insurance plan whenever circumstances change.
At Wessel Insurance, we believe insurance guidance should be tailored to the person or family making the decision. We help Maryland clients consider how life insurance may work alongside other important protections, including home insurance, auto insurance, business insurance, and Medicare insurance.
Using Term and Permanent Life Insurance Together
Many life insurance ladders are built primarily with term life insurance. However, some individuals choose to include permanent life insurance as part of their overall coverage strategy.
A smaller whole life policy may provide protection beyond temporary financial obligations. Depending on the policy, permanent life insurance may offer lifetime coverage, potential cash value accumulation, access to funds for retirement or emergencies, and living benefits in the event of a serious illness.
Combining term coverage with permanent coverage may help some people balance temporary needs with longer-range financial priorities. The right mix depends on personal goals, family responsibilities, finances, and the type of protection a person wants to maintain over time.
An Example of a Life Insurance Ladder
Consider a 30-year-old with a young family. Their life insurance plan could include several policies, each intended to serve a different purpose:
- A $250,000 policy with a 10-year term to help address student loans or debt from the early years of a career.
- A $500,000 policy with a 20-year term to help protect the mortgage and provide support while children are growing up and completing their education.
- A $250,000 whole life policy intended to help with final expenses and leave a financial legacy.
In this example, the policies are not meant to do the same job. The 10-year term policy is connected to a shorter financial timeline, while the 20-year policy addresses a longer family responsibility. The whole life policy is designed to remain in place beyond those temporary obligations.
As debts are paid down and children become financially independent, the shorter-term policies may no longer be needed. The coverage that remains can be more closely aligned with the responsibilities that still exist at that point in life.
Options as Term Policies Near Their End
Another consideration with life insurance laddering is what happens when individual term policies approach the end of their coverage periods. Many term life insurance policies include conversion features that may allow some or all of the coverage to be changed into a permanent policy without another medical exam.
This option may be valuable if health changes later make new coverage more difficult or more expensive to obtain. Rather than beginning again with a new application, a policyholder may have an opportunity to adjust their protection based on their circumstances at that time.
Conversion options vary by policy, so it is important to understand the details of any coverage under consideration. Having flexibility as life changes can bring added confidence to long-term financial planning.
Explore Life Insurance Options With Wessel Insurance
The right life insurance strategy depends on your family, financial goals, debts, and plans for the future. Life insurance laddering may be a practical option for people who want coverage that can reflect changing responsibilities over time.
Wessel Insurance Services, Inc. is an independent insurance agency serving individuals, families, and businesses throughout Jarrettsville and communities across Maryland. Our team can help you review your needs, compare life insurance options, and build a plan around the protection that matters to you. Contact us at (443) 499-2100 to discuss your life insurance needs and request personalized insurance quotes.